Personal projects, all open source. Each README describes the method, the results and the limitations.
Quantitative finance
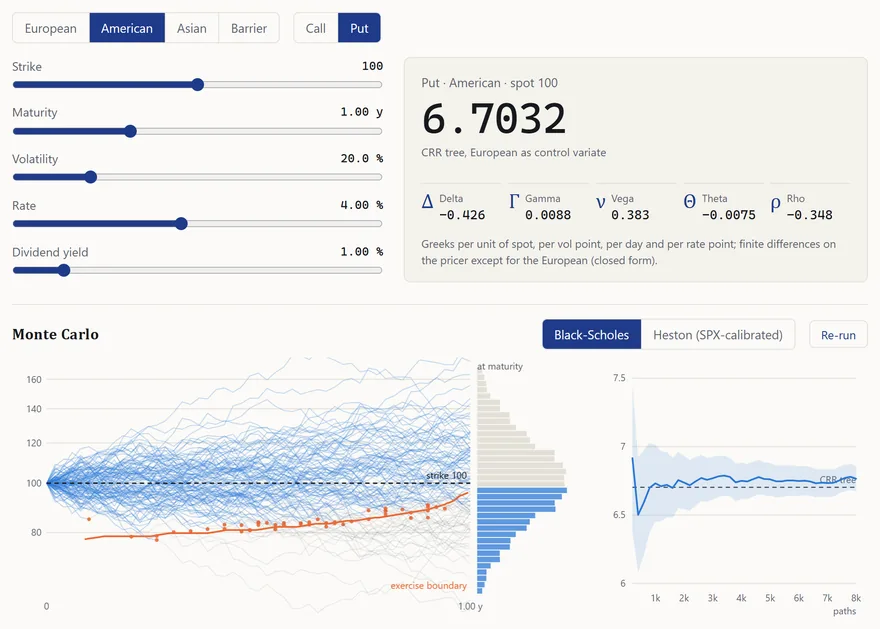
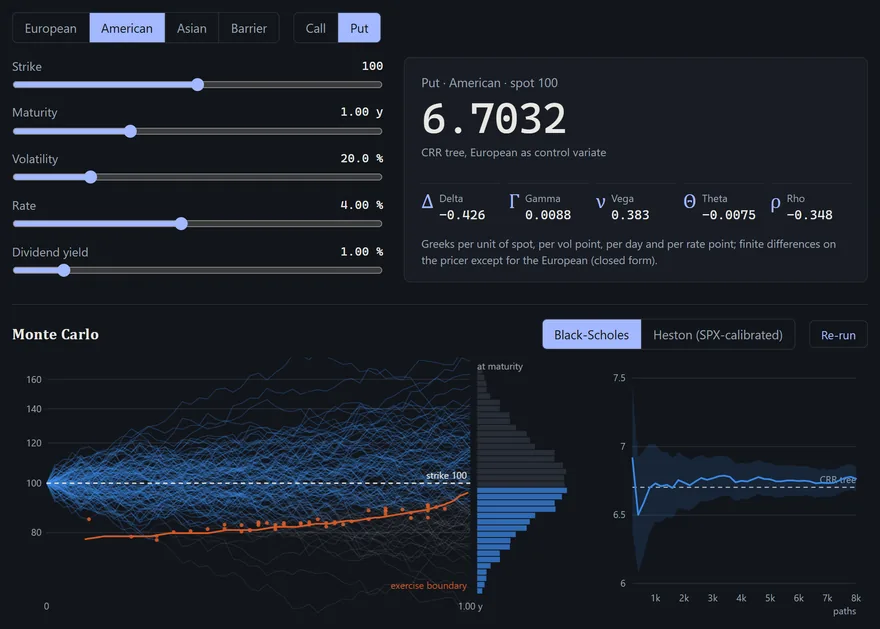
Option pricing lab
option-pricing-lab
Interactive demo ↗Runs in the browser: change the product or a parameter and the price, Greeks and Monte Carlo update.
Python library that prices European, American, Asian and barrier options under Black-Scholes, Heston, Dupire local volatility and stochastic local volatility (SLV), calibrated to SPX options.
Local volatility and SLV reprice the SPX surface within 10 bp of implied volatility, across nine maturities from two weeks to two years.
With the same vanilla prices, a one-year up-and-out call is worth 1.9% of spot under Black-Scholes and 3.5% to 4.7% under the other three models.
76 tests compare each pricer with an independent reference: closed forms, a binomial tree, Reiner-Rubinstein for barriers.
Momentum and mean-reversion signals tested on 10 assets, with daily prices from 2000 to 2025. Signals are selected on the training period only, with a Holm-Bonferroni correction, then backtested on the test period.
9- to 12-month momentum does not hold out of sample.
A 2-month contrarian signal has a Sharpe ratio of 0.11 over 2018-2025, against 0.07 for an equal-weight portfolio.
A regime-switching extension (HMM) was tested and dropped: it did not find usable regimes.
Read-only MCP server that lets Claude read desktop Outlook (mail and calendar) through COM. It needs neither Microsoft Graph nor an app registration, so it also works on accounts where these are blocked.
A test fails if the code contains any call that could modify a mailbox.
Mail content is marked as untrusted, to limit prompt injection.
Over 350 tests, run against a fake Outlook.
Built with Claude Code from a specification and safety rules I wrote.
A CNN on MFCC features labels the emotion of a voice recording (six classes, trained on IEMOCAP), Whisper transcribes it, and a small language model replies in a matching tone. CentraleSupélec project (ST7), March 2025, reworked in October 2026.
The first version loaded weights that did not match the network, so its emotion label was random. Retrained, with a test that loads the weights strictly.
On speakers never seen in training: 37% accuracy on six classes (chance: 17%). The reply only changes tone when the calibrated confidence is at least 0.45.
Runs locally on CPU: Whisper and Qwen2.5-1.5B through llama.cpp. 60 tests.
Four internships in financial markets, machine learning and data, in Paris and London. CV as PDF
Internships
–
Paris · off-cycle internship
Exotic Equity Derivatives Trader
Crédit Agricole CIB
Automated vol and correlation axes across a 1,500-stock universe from live book positions, replacing a manual desk process and saving about 4 hours a week.
Built a volatility projection engine that prices 40+ custom indices and bespoke baskets from constituent vol surfaces and correlation matrices, now used daily to set hedge ratios.
Monitored live delta, vega and gamma across 5 EMEA and AMER books (mono and multi-stock, index, single-stock dispersion), flagging exposures for intraday hedge decisions.
–
Paris · off-cycle internship
Equity Derivatives Structurer
HSBC
Cut fixed-dividend underlying pricing times by 60% by replacing a Monte Carlo/PDE computation of the stochastic volatility add-on with a generalized linear model proxy.
Priced 4,000+ client RFQs over 6 months, proposing risk-optimized payoff structures and pricing adjustments.
Structured and onboarded three payoff families with sales and trading: newly launched autocall mechanisms, equity/FX contingent options, and light exotics (variance and volatility swaps, corridors).
–
London · summer internship
Fixed Income Data Scientist
Tradeweb Markets
Built tree-based ML pricing models on 1.5M proprietary RFQ records for repo products and execution strategy.
Developed liquidity metrics and market-impact models from historical flow data to support execution benchmarking.
–
Paris · off-cycle internship
Fixed Income Trading Risk Analyst
Société Générale CIB
Built real-time risk monitoring tools (Greeks, VaR, IRC, CRM, LCR) across the full FIC perimeter, so that breaches are flagged in the morning rather than in the evening alert. Still in use after the internship.
Diagnosed limit breaches with traders, cutting the average breach duration from 3.4 to 2.2 days.
Wrote desk reports on exceptional market events (BoJ rate hike, dissolution of the French National Assembly), analysing intraday rates, credit and FX moves.
Freelance
Ongoing
Process automation
Freelance, for companies
Automation of repetitive work around the tools companies already use: ERP, invoicing, inventory management.
LLM agents where they remove manual steps.
Delivered with support and training for the people who use them.
03Education
Degrees
–
expected
MSc in Engineering (Diplôme d'Ingénieur), Computer Science major
CentraleSupélec, Université Paris-Saclay
Statistics, probability, machine learning, data science, computer vision, advanced algorithms.
Projects: second-order convex optimization for neural network training, a lightweight Linux shell in Rust.
–
Master in Management (Grande École Programme), Financial Markets major
Projects: long-short equity portfolio optimization, market price forecasting with time-series ML models.
–
Classes Préparatoires (CPGE)
Lycée Thiers, Marseille
Undergraduate preparatory programme for the French engineering school entrance exams: mathematics, physics, computer science, French literature, English.
Teaching and activities
–
President of CS Asie
Club promoting Asian cultures at CentraleSupélec
Managed a €10k annual budget and the logistics of cultural events for 500+ students.
–
Private tutoring
Tutor in Mathematics, Physics and Computer Science
Private lessons
Around ten students, from middle school to 1st/2nd-year undergraduate (classes préparatoires).
International Physics Olympiad preparation
ENS Ulm, Paris
One of 12 students selected nationwide through written exams, for theoretical and experimental training.